Research Brief
Inflation
October 2026
Broadening Price Pressures Complicate Borrowing Prospects for CRE Investors
High fuel costs could strain consumer spending. Gasoline prices rose 9.3 percent in September, marking the largest monthly increase since March. While consumer spending has remained resilient in recent months, higher fuel costs could weigh on household discretionary spending as a larger share of income is directed toward essential expenditures. Meanwhile, consumer sentiment remained subdued in early October, with the index at an uncommonly low sub-50 level. While retail vacancy has stayed close to the record lows achieved in 2024, some retailers could face headwinds if consumers pull back on spending amid expectations that inflation will remain elevated.
Housing costs remain an inflationary pressure. Shelter costs increased 0.4 percent month over month in September, the fastest pace since April, even as many multifamily markets continue to emerge from the supply-heavy conditions that characterized the last two years. Apartment vacancy remained near mid-4 percent as of September, one of its lowest readings since late 2022, while rent growth is on pace to exceed 2 percent this year, the strongest annual increase in four years. Although shelter inflation does not move in lockstep with apartment rents, the 3.1 percent annual increase in shelter costs remains above current apartment rent growth, suggesting improving multifamily fundamentals are not necessarily adding to inflationary pressure.
Key Takeaways
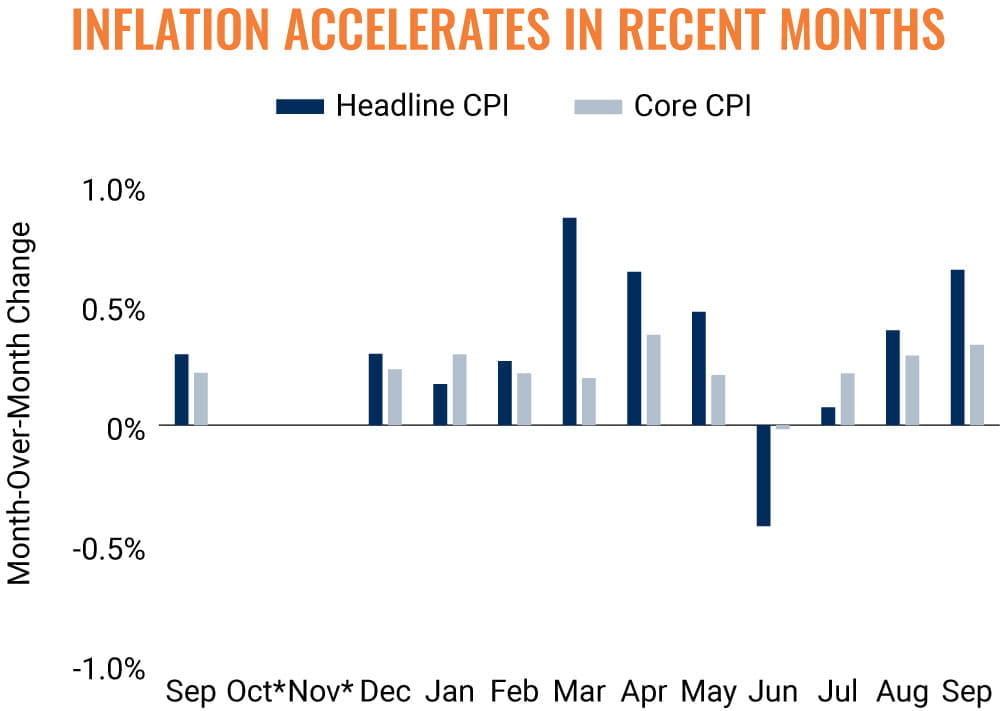
- Inflation exceeded expectations for the second consecutive month, reinforcing concerns that price pressures remain broadly entrenched.
- Financial markets are increasingly pricing in a prolonged period of restrictive monetary policy and elevated financing costs.
- Rising gasoline prices may limit consumers’ discretionary spending, creating potential challenges for some retail businesses.
- Housing-related costs also remain a contributor to persistent inflation as apartment market fundamentals continue to improve.
3.7% |
2.6% |
|
Increase in Headline CPI Year-Over-Year |
Increase in Core CPI Year-Over-Year |
* Data not available due to federal government shutdown.
Sources: Marcus & Millichap Research Services; Bureau of Labor Statistics; Federal Reserve Bank
of St. Louis; CME FedWatch.; University of Michigan: Consumer Sentiment
TO READ THE FULL ARTICLE