Research Brief
Housing
October 2026
Higher Rates Reinforce Apartment Retention, Constrain Residential Construction
Construction pipeline poised to shrink further. The Fed increase also pressures a residential construction pipeline that has already contracted. The seasonally adjusted number of residential permits in August remained more than 25 percent below its early-2022 monthly peak, while total completions declined to their lowest level since late 2018. Higher rates will increase the costs of acquisition, development, and construction for both houses and apartments, which may slow projects already facing high labor and material expenses. Homebuilders are increasingly trying to offset affordability pressures rather than stop construction: 66 percent offered sales incentives in September, including mortgage-rate buydowns and closing-cost assistance, and 38 percent reduced prices. Still, builder confidence fell to a one-year low, suggesting these measures are not fully offsetting weaker buyer demand.
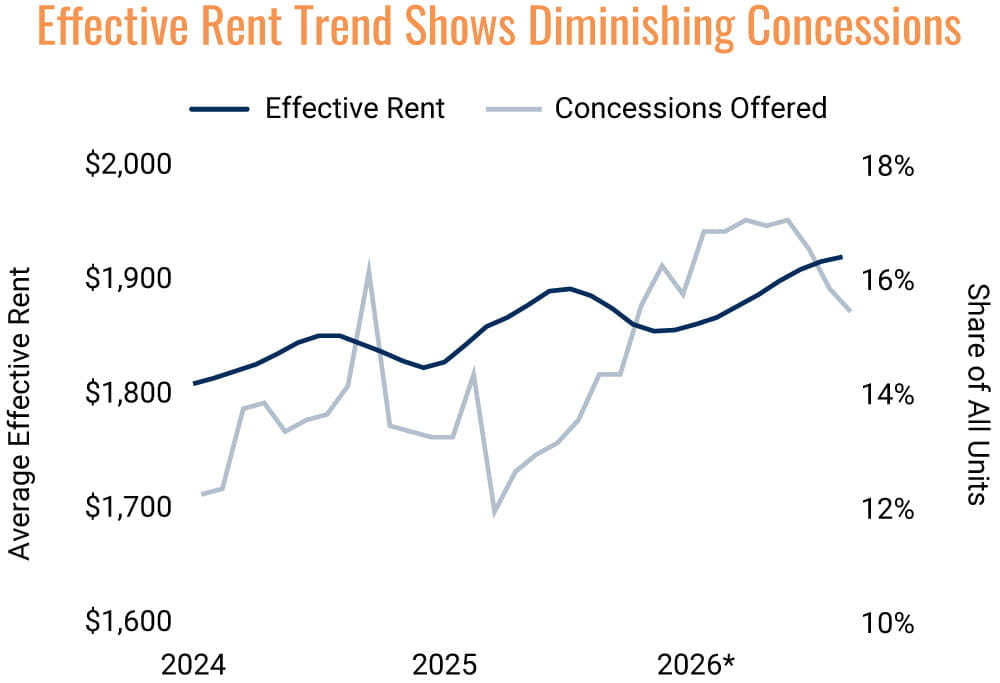
Improving operations can support investor alignment. For apartments, rising interest rates are likely to reduce acquisition leverage and refinancing proceeds, potentially widening the gap between seller expectations and buyers’ recalibrated underwriting. Although the maturity wave appears to be cresting, multifamily debt maturing over the coming year could force some borrowers, facing higher interest rates, to contribute more equity or sell when refinancing low-interest loans. Improving operations could partially offset these financing pressures, however, as slowing construction, declining concession use, and a ninth consecutive month of effective rent growth in August point to stronger property-level cash flow. These trends could strengthen confidence in future income, creating a path for better buyer-seller alignment and increased transaction activity.
Key Takeaways
- Higher mortgage rates reinforce the lock-in effect and extend renter tenure.
- Residential permit issuance remains more than 25 percent below its early-2022 peak, while completions have fallen to their lowest level since late 2018.
- Higher debt costs and upcoming loan maturities may bring apartments to market, potentially creating acquisition opportunities.
- Slowing construction and declining concession use point to improving existing multifamily performance, likely aiding buyer-seller alignment.
5.28% |
7.28% |
|
10-Year U.S. Treasury Rate |
30-Year Mortgage Rate |
* Through August Sources: Marcus & Millichap Research Services; Moody’s Analytics; National Association of Realtors; RealPage, Inc.;
Freddie Mac; Mortgage Bankers Association; National Association of Home Builders; U.S. Census Bureau; U.S. Bureau of Economic Analysis
TO READ THE FULL ARTICLE